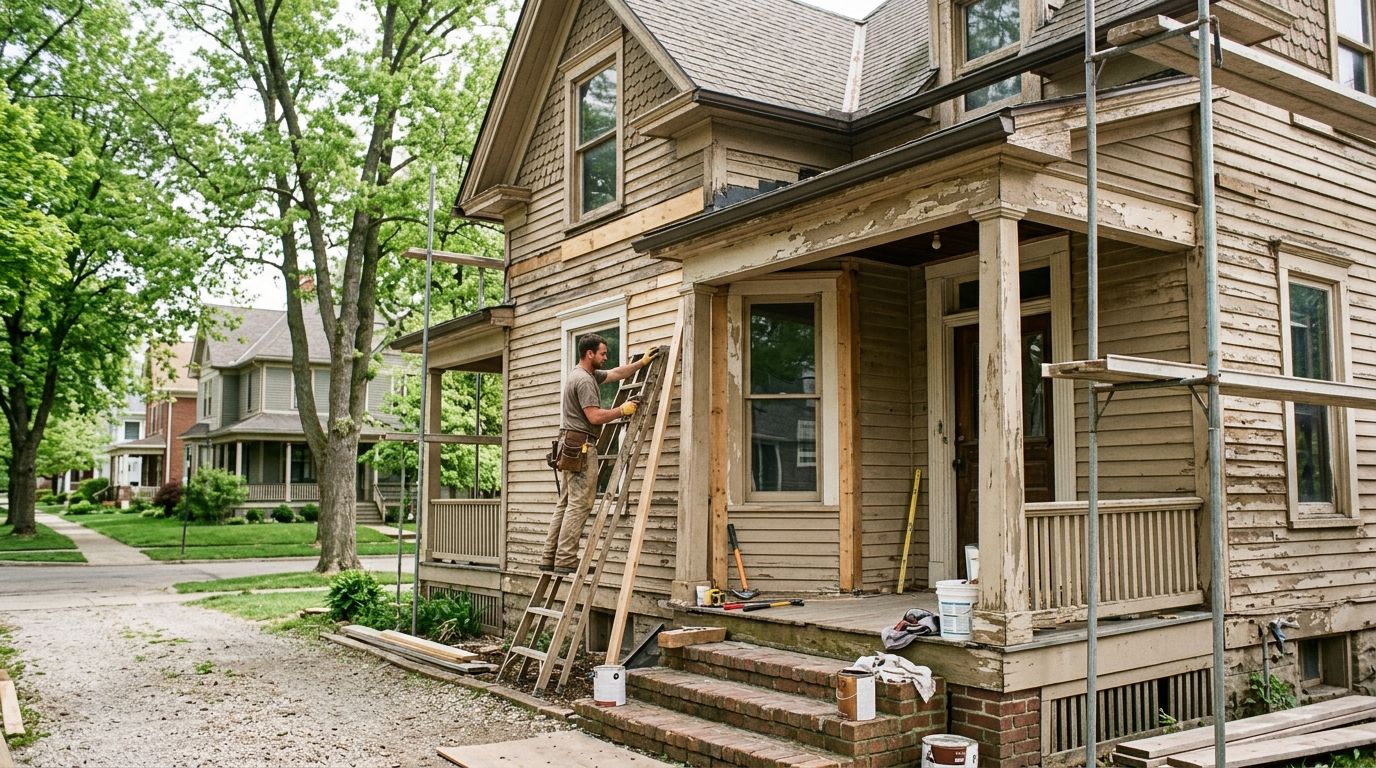
Fixer-upper homes for sale in Hamilton, OH are properties priced below move-in-ready comparables because they need cosmetic work, mechanical updates, or structural repair, with the goal of building equity through renovation instead of paying a premium for finished space. Hamilton's older neighborhoods near downtown and along the Great Miami River carry more of this inventory than newer subdivisions in Butler County, which changes how buyers should search, finance, and inspect.
- Fixer-upper homes for sale in Hamilton, OH sell below market because of deferred maintenance, not location.
- An FHA 203(k) renovation loan lets buyers finance the purchase and repairs in one mortgage.
- Permit history and inspection reports matter more here than in move-in-ready searches.
- Sandlin Realtors, led by Joey Sandlin with 20+ years of experience, negotiates repair credits and financing terms on behalf of buyers.
Why this matters
Hamilton's housing stock includes a meaningful share of older homes built before mid-century zoning updates, and many of those properties sit on the market longer simply because buyers assume the repair list is scarier than it is. A house that needs a roof and updated electrical is a different purchase than one with foundation movement, but both get labeled "fixer-upper" in listing photos.
Buyers who understand that distinction in 2026 can pick up real equity. Buyers who don't end up overpaying for cosmetic problems or underpaying attention to structural ones. The difference between a good fixer-upper and a money pit is almost always in the inspection, not the listing price.
Joey Sandlin has spent more than 20 years guiding Southern Ohio buyers and sellers through exactly this kind of purchase, and that experience carries directly into Hamilton and Butler County searches: knowing which repairs are negotiable, which lenders actually close renovation loans on time, and which neighborhoods hold value after the work is done.
How to buy a fixer-upper home in Hamilton, OH
Set your true renovation budget before you tour
Most buyers price the house, not the project. Get a rough repair estimate before you fall for a listing.
- Walk the exterior first: roof age, foundation cracks, drainage away from the house
- Price major systems separately: HVAC, electrical panel, water heater
- Add 15-20% contingency on top of any contractor estimate
- Confirm what your lender will and won't finance as part of the purchase
Search Hamilton listings tagged as-is, handyman, or estate sale
These labels signal seller-side awareness that the home needs work, which usually means more room to negotiate.
- Filter for "as-is" and "needs TLC" in listing remarks
- Check days-on-market; longer listings often have more negotiating room
- Look at estate sales and probate listings for motivated sellers
- Cross-reference tax records for absentee owners who may want a fast close
Check the home's permit history before you write an offer
Unpermitted work is the single biggest hidden cost in a fixer-upper purchase. A finished basement or converted garage without a permit can mean redoing the work to code, and lenders sometimes flag it during appraisal.
Review how to check a home's permit history in Ohio before you get attached to a specific property, not after your offer is accepted.
Order a full inspection, not a walkthrough
A standard inspection covers the basics. A fixer-upper needs specialists.
- General home inspection covering structure, roof, and systems
- Sewer scope if the home is more than 40 years old
- Electrical panel inspection if wiring looks original
- Pest and wood-rot inspection for older framing
- Radon test, standard in most Ohio purchase contracts
Line up financing that covers the repair budget
Cash buyers skip this step, but most buyers need a loan that finances both the purchase and the renovation. An FHA 203(k) loan folds both into a single mortgage with a minimum 3.5% down payment, which keeps buyers from needing a second loan for repairs. Compare that against a conventional renovation loan or a HELOC on a separate property if you already own a home.
Read how to buy a home with a renovation loan in Cincinnati for the loan-by-loan breakdown before you talk to a lender.
Negotiate repair credits instead of asking for full fixes
Sellers of fixer-uppers rarely want to manage contractors before closing. A repair credit at closing keeps the deal moving and lets you control the renovation timeline and contractor.
- Ask for a credit tied to the inspection report, not a vague discount
- Get contractor quotes before you name a credit amount
- Keep major structural items (roof, foundation, HVAC) as separate negotiating points
- Don't let cosmetic items (paint, flooring, fixtures) eat into your leverage on real repairs
This is where working with an agent who has negotiated dozens of these deals pays off. Sandlin Realtors handles the back-and-forth on repair credits and financing contingencies so buyers aren't negotiating against an experienced listing agent alone.
“If the roof, foundation, and mechanicals check out, everything else on a fixer-upper is just labor and paint.”
Comparing your options for buying a fixer-upper in Hamilton
| Option | Best for | Key limitation |
|---|---|---|
| Standard MLS as-is listing | Buyers who want inspection contingencies intact | Competition from other renovation-focused buyers |
| HUD home purchase | Buyers comfortable with a bidding period and as-is sale terms | No seller repairs or credits negotiated |
| Foreclosure purchase | Buyers seeking the deepest discount on price | Property condition often unknown until after close |
| Off-market estate or probate sale | Buyers who want less competition and more negotiating room | Longer timelines while estate or court processes finalize |
For HUD-specific rules, how to buy a HUD home in Southern Ohio covers the bidding window and owner-occupant priority period.
Talk to Joey Sandlin about Hamilton fixer-uppers
Get guidance on inspections, financing, and repair-credit negotiation before you offer.
Common mistakes Hamilton fixer-upper buyers make
- Skipping the sewer scope on pre-1980 homes. Hamilton's older sewer lines fail quietly, and a scope costs far less than a surprise excavation after closing.
- Underestimating permit gaps. A converted attic or basement without a permit can stall your own appraisal or resale down the line.
- Financing repairs with a credit card or personal loan. A 203(k) or renovation loan almost always costs less over the life of the project.
- Assuming every "handyman special" is a deal. Some are priced correctly for the work needed; run your own numbers before assuming a discount exists.
- Waiving the inspection to compete on price. On a fixer-upper, the inspection is the deal, not a formality.
FAQ
What counts as a fixer-upper home in Hamilton, OH?
A fixer-upper in Hamilton is any listing priced below comparable move-in-ready homes because it needs cosmetic work, system updates, or structural repair. The condition range spans from minor paint and flooring jobs to homes needing new roofs, electrical, or foundation work.
Is it better to buy a fixer-upper or a move-in-ready home in Hamilton?
A fixer-upper makes sense if you have renovation financing lined up and realistic repair estimates; a move-in-ready home makes sense if you want to avoid contractor management. Both can build equity, but fixer-uppers require more upfront diligence on inspections and permits.
How much does it cost to renovate a fixer-upper in Hamilton, OH?
Renovation costs depend entirely on the scope of work, from a few thousand dollars for cosmetic updates to well into six figures for full structural repair. Get contractor quotes on the specific property before making an offer rather than relying on a general estimate.
Can you use an FHA loan to buy a fixer-upper in Hamilton?
Yes, an FHA 203(k) renovation loan finances both the purchase price and eligible repairs in a single mortgage with a minimum 3.5% down payment. It requires a licensed contractor and a scope of work approved by the lender before closing.
Should I get a home inspection on a HUD or foreclosure fixer-upper?
Yes, even though HUD and foreclosure sales are typically sold as-is with no seller repairs. The inspection tells you what you're actually buying and whether the price still makes sense once repair costs are factored in.
How do I check if renovation work on a Hamilton home was permitted?
Butler County and the City of Hamilton keep permit records that show whether additions, basement finishes, or electrical work were done to code. Unpermitted work can complicate financing and resale, so check this before writing an offer.
Are fixer-upper homes in Hamilton a good investment in 2026?
They can be, provided the structural systems (roof, foundation, electrical) are sound and the renovation budget is realistic. The equity gain comes from buying below the cost of comparable finished homes, not from underestimating the repair list.
One last thing
The fixer-upper homes that turn out well in Hamilton almost always have one thing in common: the buyer got the sewer scope, the permit history, and a real contractor estimate before writing the offer, not after. Skip any one of those three and the "deal" price stops meaning much.


